Top 5 Financial Ratios Every Investor Should Know
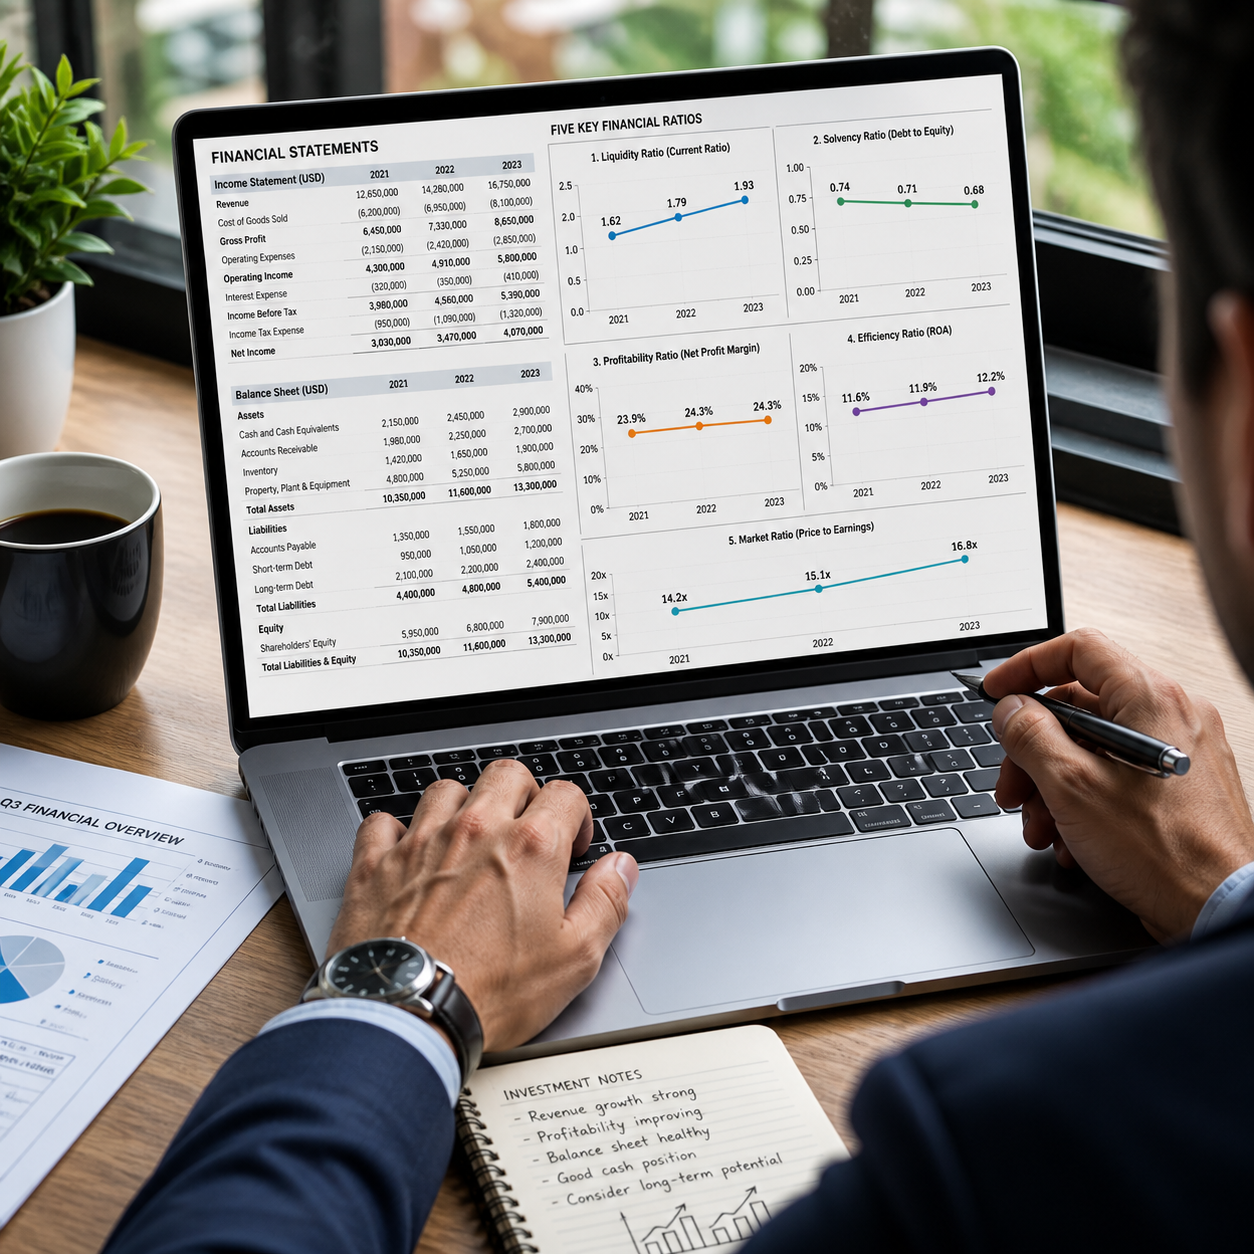
Financial ratios help investors turn a company’s financial statements into clear, comparable signals. By studying valuation, profitability, leverage, and liquidity, you can form a more disciplined view of a business before researching its stock further.
The most useful ratios are not automatic buy or sell signals. They are screening and comparison tools that work best alongside the income statement, balance sheet, cash flow statement, industry benchmarks, and qualitative research.
Why Financial Ratios Matter to Investors
Financial ratios make company performance easier to compare by relating figures from the income statement, balance sheet, and cash flow statement to one another. They help investors assess whether a stock appears expensive, profitable, heavily indebted, or capable of meeting short-term obligations.
A company might report rising revenue, for example, but that growth means less if debt is also increasing rapidly or cash flow remains weak. Ratios provide a structured way to investigate those relationships.
- Valuation ratios show how the market prices earnings or assets.
- Profitability ratios indicate how efficiently a company uses capital.
- Leverage ratios reveal how much financial risk debt may create.
- Liquidity ratios measure the ability to cover near-term obligations.
Use a three-part comparison: examine the company’s current result, its trend over several years, and its position against similar businesses. A ratio that looks attractive in isolation may be normal, weak, or misleading within its industry.
1. Price-to-Earnings Ratio (P/E)
The price-to-earnings ratio (P/E) compares a company’s share price with its earnings per share (EPS). Its basic formula is: P/E = market price per share ÷ earnings per share.
If a stock trades at $60 and generates $3 in EPS, its P/E is 20. In simple terms, investors are paying $20 for each dollar of the company’s current annual earnings.
A high P/E can indicate that the market expects strong future growth, durable competitive advantages, or lower business risk. It can also mean the stock is overpriced. A low P/E may signal an undervalued company, but it may equally reflect falling earnings, cyclical conditions, weak management, or serious financial risk.
How investors use P/E
Compare P/E with companies in the same industry and with the company’s own historical range. Fast-growing software companies often trade at higher P/E multiples than mature utility companies because investors expect different growth and stability.
Check whether the calculation uses trailing earnings or forecast earnings. Trailing P/E relies on reported results, while forward P/E uses estimates that may prove inaccurate. P/E also becomes less useful when earnings are negative or temporarily distorted by exceptional items.
2. Debt-to-Equity Ratio (D/E)
The debt-to-equity ratio (D/E) measures financial leverage by comparing a company’s total debt with shareholders’ equity. The formula is: D/E = total debt ÷ shareholders’ equity.
Suppose a company has $400,000 in debt and $800,000 in equity. Its D/E ratio is 0.5, meaning it uses 50 cents of debt for every dollar of shareholder equity.
Debt can help a company expand without issuing more shares, which may improve returns when the borrowed money produces strong profits. The trade-off is fixed interest and repayment obligations. During a downturn, highly leveraged businesses have less financial flexibility and may face refinancing pressure.
A low D/E generally suggests lower balance-sheet risk, but it is not automatically superior. Some stable businesses can use moderate debt efficiently, while companies with unusually low debt may be growing more slowly or failing to invest.
How to interpret leverage
Compare D/E with industry benchmarks, interest costs, cash flow, and the company’s debt maturity schedule. Capital-intensive industries commonly carry more debt than asset-light businesses. Also check whether the reported equity base has been reduced by share buybacks, which can make D/E appear unusually high even when debt has not changed much.
3. Return on Equity (ROE)
Return on equity (ROE) measures how much profit a company generates from shareholder equity. The basic formula is: ROE = net income ÷ average shareholders’ equity × 100.
A business earning $50 million in net income on average equity of $250 million has an ROE of 20%. This means it generated 20 cents of profit for each dollar invested by shareholders during the period.
Investors often value a consistently strong ROE because it suggests that management uses shareholder capital effectively. However, a high ROE can result from genuine operating strength or from heavy borrowing. Debt reduces the amount of equity supporting the business, which can mathematically increase ROE while also increasing risk.
Use ROE with D/E and earnings quality
Review ROE over at least three to five years rather than relying on one unusually profitable period. Then compare it with D/E, revenue growth, operating margins, and cash flow.
For example, a company may report a 25% ROE after taking on substantial debt and repurchasing shares. Another company may produce a 19% ROE with a stronger balance sheet and more dependable cash generation. The second result could be more resilient, even though its headline ROE is lower.
4. Current Ratio
The current ratio measures whether a company has enough current assets to cover current liabilities due within roughly one year. The formula is: current ratio = current assets ÷ current liabilities.
If current assets total $900,000 and current liabilities total $600,000, the current ratio is 1.5. On a basic accounting view, the company has $1.50 of current assets for every $1 of short-term obligations.
Current assets may include cash, marketable securities, inventory, and accounts receivable. Current liabilities commonly include accounts payable, short-term borrowings, and other obligations due soon.
A very low current ratio can indicate liquidity pressure, especially if cash flow is weak or inventory is difficult to sell. A higher ratio may provide a larger safety cushion, but an excessively high figure can also suggest idle cash, slow-moving inventory, or inefficient working-capital management.
Look beyond the headline number
Two companies with the same current ratio may have very different risk profiles. One might hold mostly cash and high-quality receivables; the other might depend on selling obsolete inventory. Read the balance sheet notes and compare the ratio with operating cash flow, payment terms, and seasonal patterns.
5. Price-to-Book Ratio (P/B)
The price-to-book ratio (P/B) compares a company’s market value with the book value of its net assets. Its common formula is: P/B = market price per share ÷ book value per share.
Book value represents assets minus liabilities on the balance sheet. If a company’s share price is $30 and its book value per share is $20, its P/B is 1.5.
P/B can be particularly useful for banks, insurers, manufacturers, and other asset-heavy businesses where balance-sheet assets play a central role in generating income. A low P/B may indicate a potentially undervalued stock, but it may also reflect poor asset quality, weak profitability, or a business model in decline.
The ratio is less informative for companies whose value comes mainly from software, brands, patents, customer relationships, or employee expertise. Many internally developed intangible assets do not appear fully on the balance sheet, so book value may understate economic value.
Compare P/B with ROE. A company trading above book value may justify that premium if it consistently generates strong returns on equity. A low P/B paired with weak ROE deserves more investigation rather than automatic enthusiasm.
How to Use Financial Ratios Together
Use the five ratios as a compact diagnostic framework: valuation, leverage, profitability, liquidity, and asset value. Reviewing them together reduces the risk of making a decision from one attractive number.
- Start with valuation: Compare P/E and P/B with peer companies and historical ranges.
- Test profitability: Use ROE to see whether the business turns shareholder capital into earnings.
- Check leverage: Examine D/E to determine whether debt supports growth or magnifies vulnerability.
- Check liquidity: Review the current ratio and cash flow for evidence that near-term bills can be paid.
- Investigate the statements: Read the income statement, balance sheet, cash flow statement, and management discussion before drawing conclusions.
A useful mental model is the “four-corner test.” A potentially robust business often combines a reasonable valuation, durable profitability, manageable leverage, and adequate liquidity. It does not need to score perfectly in every category. Instead, identify which corner is weakest and decide whether that weakness is temporary, structural, or already reflected in the stock price.
Limitations of Financial Ratios
Financial ratios are informative but incomplete because they depend on accounting choices, timing, industry conditions, and historical data. They should support research, not replace it.
- Industry differences: A D/E or current ratio that is normal for a bank may be inappropriate for a retailer or technology company. Compare like with like.
- Accounting policies: Depreciation methods, inventory valuation, leases, acquisitions, and share buybacks can affect reported ratios.
- Exceptional items: Asset sales, restructuring charges, lawsuits, or tax benefits can temporarily distort earnings and ROE.
- Historical limitations: A five-year trend describes what happened, not what must happen next.
- Cash-flow gaps: Profit does not always convert into cash. Review operating cash flow and capital expenditure alongside earnings.
Common mistakes include treating a low P/E as proof of value, celebrating high ROE without checking debt, and comparing unrelated industries. Correct these errors by defining the peer group first, normalizing unusual events where possible, and reading the complete financial statements.
Frequently Asked Questions
What is the most important financial ratio for investors?
There is no universally most important ratio. P/E may matter most for a profitable growth company, while P/B and ROE may be especially useful for a bank. The right choice depends on the business model and investment question.
How do I compare financial ratios between companies?
Compare companies in the same industry, with similar business models and reporting periods. Review current figures, multi-year trends, and relevant industry benchmarks rather than relying on a single peer comparison.
Are high financial ratios always good?
No. A high ROE can reflect excessive debt, and a high current ratio can reflect inefficient assets. A high P/E may signal growth expectations or overvaluation. Interpretation depends on context.
How often should investors review financial ratios?
Many investors review ratios when quarterly or annual results are released, then investigate major changes. Long-term investors can focus on meaningful trends rather than reacting to every short-term movement.
Can financial ratios predict stock performance?
Ratios cannot reliably predict future stock performance on their own. They can improve analysis by revealing valuation, financial strength, and business risks, but market conditions, execution, competition, and unexpected events still matter.
For beginners, the strongest process is straightforward: calculate or verify the five ratios, compare them with appropriate peers, study their direction over time, and connect the numbers to cash flow and business quality. That approach produces better questions, which is what financial ratios are designed to do.